| Unsubscribe |
Dear Fellow Investor,
You've probably heard AI data centers are booming.
Going up everywhere.
Bigger.
More expensive.
And supposedly unstoppable.
But here's what nobody's telling you:
Across America, residents are showing up at town halls... DEMANDING these projects be stopped.
Some have already been delayed.
Others have been canceled outright.
Billions in Big Tech investment is running into a wall of local resistance.
Not a prison.
Not a landfill
I'm talking about the giant data centers powering artificial intelligence.
People are fed up with the constant noise.
The enormous water demands.
And the strain these facilities place on local power grids...
Boosting the local resident’s electric bills.
Too many investors see these protests and think one thing:
"Bad news for AI."
But futurist and investing expert George Gilder sees something completely different.
And when he talks, you should listen:
Gilder predicted Netflix in 1994.
The iPhone in 1991.
And Amazon in 1996.
Years before investors saw gains of 112,700%, 249,900%, and 216,100%.
Today, he believes AI is approaching a critical bottleneck.
Not because demand is slowing.
But because the infrastructure supporting it is becoming harder, slower, and more expensive to build.
And history shows that whenever a dominant technology hits a bottleneck...
A new architecture emerges to replace it.
That's why Gilder says three little-known companies have quietly developed technology...
That could BYPASS the need for many of tomorrow's mega-sized AI data centers altogether.
The more expensive these facilities become...
The more politically toxic they become...
And the harder they are to build...
The more valuable this alternative technology becomes.
That's why some of the smartest money in tech is already moving.
And why the early investing window may be closing faster than people realize.
See the three companies before Wall Street catches on.
To the future,
Roger Michalski
Publisher, Eagle Financial Publications
P.S. Here's the part nobody on Wall Street has said out loud:
The angrier the public gets, the stronger the investment case for these three companies becomes.
P.P.S. The protesters think they're slowing AI data centers down. They may actually be accelerating the shift to an entirely new way of powering it.
Don’t Get NVIDIA’s Reflection AI Interest Wrong: Its Moat Could Deepen
Authored by Thomas Hughes. Date Posted: 10/14/2026.
Key Points
- NVIDIA is reportedly exploring a deal to acquire or expand its stake in Reflection AI, a startup building open-weight foundation models and agentic tools.
- Such a deal would likely reinforce NVIDIA's hardware-centric moat rather than shift its strategy, though it could draw regulatory scrutiny similar to its Groq arrangement.
- With a consensus Buy rating from 55 analysts and roughly 40% implied upside, NVIDIA heads into its Nov. 18 earnings report amid decelerating but still strong growth forecasts.
- Special Report: Grand Canyon Discovery Reshapes America's Energy Tax Credits.
Being AI-lab agnostic has long been a pillar of NVIDIA’s (NASDAQ: NVDA) strategy. Selling to all labs creates a deep moat, making the question of which one wins almost moot: NVIDIA benefits because it sells hardware, ecosystems, and services to the industry. For now, that moat is based largely on silicon, but it deepens with every advancement across the stack, further entrenching the company as a comprehensive, universal AI development ecosystem.
So, what happens when the company breaks out of its mold? Speculation is mounting that this is becoming increasingly likely. NVIDIA is reportedly in early talks to acquire Reflection AI or increase its investment in the startup. Reflection AI is a newer company founded by former Alphabet (NASDAQ: GOOGL) DeepMind researchers.
Trump goes "all-in" on Grand Canyon energy breakthrough (Ad)
A drilling crew near the Grand Canyon uncovered a clean energy well producing nearly eight times the output of Saudi Arabia's largest oil field, with potential to last two million years.
While the One Big Beautiful Bill Act eliminated federal credits for solar, wind, and EVs, this energy source was reclassified alongside oil and nuclear power and given eight years of tax credits. Google signed a 15-year contract, and Bill Gates committed $100 million.
One company controls the entire supply chain behind this discovery.
See the ticker behind this Grand Canyon energy breakthrough nowReflection AI focuses on open-weight foundation models, which aren't necessarily fully open-source, and agentic software tools designed to democratize AI. Governments, enterprises, and AI labs can download the software, own and customize it, and run AI models on their own hardware. Its offerings include Beam, which focuses on coding, reasoning, and agentic tasks, and Asimov, an agentic tool that helps developers answer complex questions about software systems.
NVIDIA’s Moat Will Deepen If It Acquires Reflection AI
Investors should note that this move wouldn't necessarily alter NVIDIA's strategy; it could strengthen it. Owning a developer of open-weight AI tools would help NVIDIA deepen its moat. Making AI models more widely accessible keeps the focus on its hardware and ecosystem rather than on which model developer wins.
The likely outcome is that model developers and, more importantly, inference providers will continue investing in NVIDIA technology as demand for AI-enabled enterprise and consumer services grows. It's not just about the models but also the equipment used to run them. Models are already a dime a dozen; the question for businesses and consumers is which ones to use and how to access them. This move could cement and strengthen NVIDIA’s revenue and earnings outlook as the AI industry expands.
And NVIDIA isn’t new to the business. NVIDIA previously made an $800 million direct investment in Reflection AI, anchoring a $2 billion funding round that valued the company at $8 billion. The partnership not only provides Reflection AI with funding but also strengthens its ties to NVIDIA's GPU ecosystem, which it uses to train its models. Nebius Group (NASDAQ: NBIS) is another critical player, having secured a $1 billion contract from Reflection AI for cloud capacity and services.
The question of whether owning a model maker would give NVIDIA a new revenue stream or strain its relationships with AI labs remains open. NVIDIA may be more interested in Reflection AI for its position in the AI ecosystem than for its revenue. If NVIDIA wants to keep low-cost, open-weight AI models under Western control, an acquisition could be strategically valuable. The risk is that China emerges as the leader in low-cost models, leading the industry toward its hardware and ecosystem rather than NVIDIA’s.
NVIDIA Will Control Reflection AI; the Only Question Is How
The most important question is how the deal might be structured. Investors should consider the possibility of a nonstandard workaround, such as a hire-to-acquire strategy, although even that is not assured. NVIDIA may simply hire Reflection AI’s staff and license its technology, potentially avoiding a lengthy merger review without necessarily escaping regulatory scrutiny.
Regulatory oversight also poses risks, as authorities have already expressed interest in other deals. NVIDIA licensed technology from Groq and hired several of its executives, a company also founded by former Alphabet engineers. The arrangement raised questions from lawmakers about whether NVIDIA intentionally avoided regulatory oversight.
Those raising concerns include Senators Elizabeth Warren and Richard Blumenthal, who argue that NVIDIA’s dominance in AI may pose a threat to competition. In this environment, the company will have to address regulatory concerns carefully.
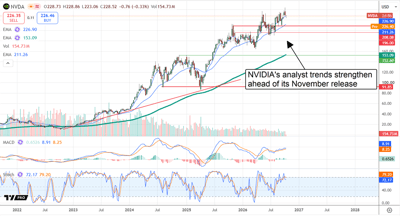
Analysts remain bullish on NVIDIA, although the potential deal’s impact remains uncertain. The acquisition could represent an extension of NVIDIA's strategy rather than a strategic shift. The stock carries a consensus Buy rating from the 55 analysts tracked by MarketBeat, with a consensus price target suggesting more than 40% upside from mid-October trading levels.
NVIDIA’s next visible catalyst is its upcoming earnings report. Expected around Nov. 18, the report is expected to show a deceleration to about 90% year-over-year revenue and earnings growth. The company consistently outperforms estimates and could do so again this quarter. Global investment in AI infrastructure across industries continues to drive demand for its core products. Investors will be watching growth as well as profitability, cash flow, and capital returns, all of which have been accelerating.
Why Wall Street Expects Even More From SanDisk After Its 575% Rally
By Sam Quirke. First Published: 10/11/2026.
Key Points
- SanDisk shares have surged 575% in 2026, and multiple analysts, including Mizuho, Rosenblatt and Arete Research, have recently raised their price targets further.
- Wall Street's optimism stems from durable AI-driven demand for data-center storage, longer-term supply contracts, and more disciplined capacity expansion across the memory industry.
- Risks remain, including reliance on consumer gadget sales, potential oversupply from rivals, and the possibility that earnings are nearing a cyclical peak ahead of this month's report.
- Special Report: Grand Canyon Discovery Reshapes America's Energy Tax Credits.
Few stocks have had a year quite like SanDisk Corporation (NASDAQ: SNDK). The memory-chip maker has surged a remarkable 575% so far in 2026, turning a once little-known name into one of the market's standout performers. After a brutal summer correction, its shares now trade around $1,600, up nearly 60% from their July low in a steady march of higher highs.
A move of that size would normally have investors thinking about taking some profits, concerned that the easy money has already been made.
Do NOT Buy SpaceX – Do This Instead (Ad)
SpaceX just went public - and Whitney Tilson, Harvard MBA and 30-year Wall Street veteran, says buying in could be a costly mistake. He calls it among the most overhyped, overvalued large-cap offerings ever pushed onto everyday investors.
Tilson believes a rare economic event is approaching - one with serious consequences for your portfolio this summer. He has prepared a free analysis outlining what he sees and the specific steps he recommends taking now.
Read Tilson's free analysis and find out what to do with your moneyYet Wall Street appears to be doing the opposite. Over the past fortnight—and, indeed, the past few months—a string of analysts have raised their price targets, betting that even after this spectacular climb, SanDisk has further to run.
So what has the market so excited about a company making something as unglamorous as flash memory?
And with earnings due at the end of the month, could the final stretch of the year deliver yet another leg higher?
The Analysts Are Piling In
The recent run of bullish calls is hard to ignore. Just this week, Mizuho lifted its price target to $2,050 from $1,875, pointing to surging demand for memory tied to agentic AI. That followed a flurry of even more ambitious targets in recent weeks, including a $2,400 call from Rosenblatt at the end of last month and an eye-catching $3,000 target from Arete Research in August. From the stock's current level, that target implies upside of nearly 90%.
The bull case is no longer based solely on the boom-and-bust cycles that have long defined the memory industry. Instead, it centers on a new and potentially far more durable source of demand.
That demand is being driven by the way AI is used. As the focus shifts from training models to running them at scale, the systems doing the work need vast amounts of fast, high-capacity storage to hold the data they draw on. It is a less visible corner of the AI build-out than chips, but a growing one, and SanDisk sits squarely within it.
Why This Boom May Last
The bull case is that SanDisk is becoming less reliant on the volatile spot market for memory chips. Increasingly, it is locking in customers through longer-term contracts that guarantee both volumes and a price floor, giving it visibility into future revenue that the industry has rarely enjoyed.
Just as important is the shift in its customer base. A growing share of the business now comes from data centers rather than the fickle phone and laptop markets, and that enterprise demand tends to be far more dependable. The company has been deliberately steering production toward these higher-value, AI-driven applications.
There is a supply angle, too. Rather than flooding the market with new capacity, as memory makers have done in the past, SanDisk has been expanding output more carefully. If the industry as a whole shows similar discipline, pricing could remain healthier for longer, avoiding the gluts that have historically ended rallies.
A Word of Caution
For all the enthusiasm, however, this is still the memory business, and a degree of caution is warranted. The central concern is timing, with bears arguing that SanDisk's earnings may be near a cyclical peak. In other words, buying now risks paying up just as the cycle is preparing to turn. Even the stock's comparatively low valuation could prove expensive if it is applied to profits that begin to fade.
The other risks are not hard to spot. A meaningful share of SanDisk's sales still depends on consumer gadgets, where demand could weaken. At the same time, fresh capacity from rivals, including fast-growing Chinese manufacturers, could revive the oversupply that has haunted the sector in the past. The contracts help, but they do not make the company immune.
That makes the company's earnings report later this month all the more important. After a rally this large, a simple beat may not be enough; investors will be looking for reassurance on pricing, contract coverage, and whether management believes its fat margins are built to last.
A Rally With Room to Run
Weighing it all up, SanDisk remains a compelling way to play the AI storage boom. The combination of buoyant demand, improving contract visibility, and a growing data-center business has convinced much of Wall Street that its transformation is real and that the shares can climb further despite their stunning ascent.
The cyclical risks are real, and anyone buying after a 575% run should do so with eyes open. But with analysts lining up behind ever-higher targets and a potential catalyst just weeks away, momentum remains firmly with the bulls. For investors who believe AI's hunger for storage is only beginning, SanDisk's extraordinary year may still have another chapter left to write.
This message is a sponsored email provided by Eagle Publishing, a third-party advertiser of Earnings360 and MarketBeat.
If you need assistance with your newsletter, don't hesitate to email our U.S. based support team at contact@marketbeat.com.
If you no longer wish to receive email from Earnings360, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 North Reid Place, Sixth Floor, Sioux Falls, South Dakota 57103-7078. U.S.A..