 A Message From Porter & Company There’s a secret type of finance you don’t know about. For hundreds of years it has been used by the world’s wealthiest families… The Rothschilds, the Morgans, the Fuggers, the DuPonts, the Rockefellers, the Barings, the Lloyds, the Oppenheimer family… they allused it to grow their fortunes. 
Even today, this ancient investment is still quietly used by many of the world’s wealthiest people, because as legendary investor Joel Greenblatt says, “it’s the closest thing to a perpetual motion machine you will ever see.” Yet almost nobody has heard of it. Even fewer know how to use it to grow their wealth. But that ends now because I’m revealing the secret of my Perpetual Money Machine… an investment that has historically outperformed the S&P 500 by almost 10x over the last 40 years. In my new documentary I pull back the curtain on this secret type of finance… reveal its fascinating origins… and, most importantly, show you how to use it to potentially create your own financial results. Simply click here to stream my new documentary at no cost. I’ve been writing about financial markets for almost thirty years. And this story is one of the most remarkable I’ve ever encountered: an investment that isn’t just “built” to perfection but can also deliver returns that are so endless one man used it to turn $50,000 into $900,000,000 - an exceptional, atypical individual result. You’ve never seen anything like this before. Good investing, Porter Stansberry
Today's Featured Article
Ride-Share Reckoning: Tesla Drives Into Uber's LaneBy Jeffrey Neal Johnson. Article Posted: 9/7/2026. 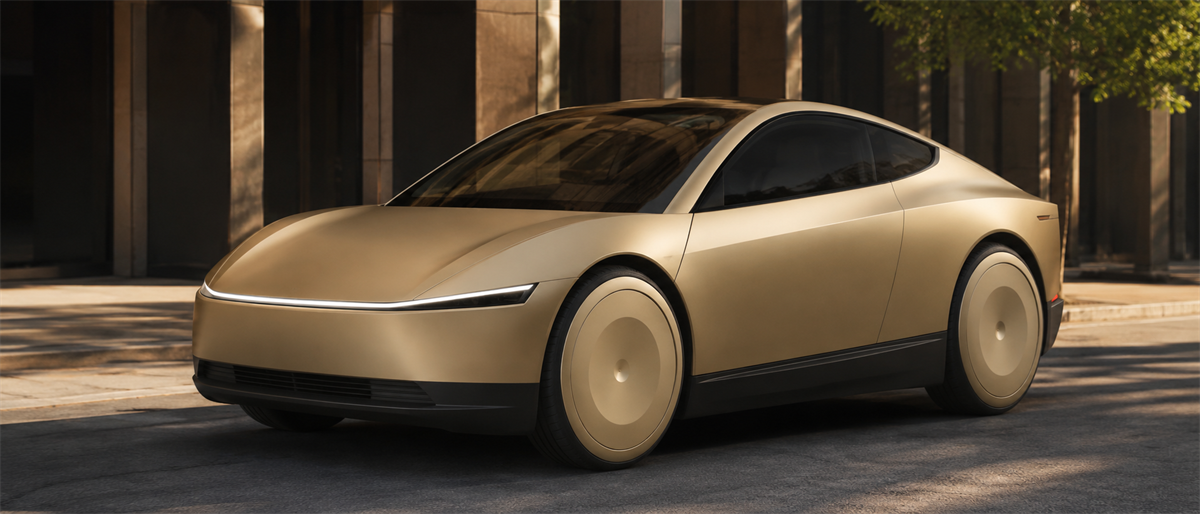
Key Points
- Tesla trades at a trailing price-to-earnings ratio near 326 as investors price in future robotaxi software revenue rather than current hardware margins.
- Uber trades at a discounted trailing price-to-earnings ratio of about 17 despite stronger net margins, reflecting market concern over driverless competition.
- Regulatory progress, including French testing of about 195,000 kilometers with no incidents, remains a key bottleneck for scaling autonomous fleet revenue.
- Special Report: The REAL Reason Trump is Invading Iran
Evaluating the electric vehicle and autonomous transportation sectors requires looking beyond traditional metrics, such as vehicles produced and delivered. Wall Street is increasingly focused on recurring software revenue and fleet utilization. The shift away from consumer retail sales and toward commercial robotaxi fleets is changing the sector's underlying fundamentals. Understanding this dynamic helps clarify the aggressive growth multiples assigned to autonomous innovators compared with the discounted valuations given to legacy ride-share companies. The recent deployment of vehicles without steering wheels in Austin signals a structural shift in how automotive technology is valued, bringing execution risk and regulatory timelines to the forefront. Driving Margins: The Cybercab Software Pivot
This recent rollout of steering-wheel-free vehicles in Texas marks a necessary evolution for Tesla, Inc. (NASDAQ: TSLA). For years, Tesla operated primarily as a traditional hardware manufacturer, relying on direct-to-consumer vehicle sales to drive top-line revenue. That model is facing margin compression across the industry. Recent financial data show Tesla operating with a net margin of about 3.6% and a return on equity of nearly 3.8%. These metrics highlight the operational strain inherent in building and selling physical hardware in a highly competitive, capital-intensive environment. The recent downgrade of Tesla's financial health into TradeSmith's Yellow zone underscores the short-term capital pressure involved in scaling new infrastructure. The Austin launch is not simply a new product reveal; it is the physical deployment of a business model designed to unlock higher-margin fleet revenue. A commercial robotaxi network would replace one-time hardware sales with continuous software monetization and utilization fees. If successful, this ecosystem would fundamentally change Tesla's cash flow profile, moving it closer to a software-as-a-service model. The vehicle would essentially become the delivery mechanism for proprietary software, allowing Tesla to capture ongoing revenue for every mile driven rather than recognizing a single transaction at the point of sale. The capital expenditure required for autonomous-driving technology is substantial, but the potential recurring revenue base offers a clear path out of the low-margin manufacturing cycle. Valuation Traffic Jam: Pricing the Software PremiumUnderstanding this shift requires a close look at current market multiples and what they imply for future earnings. Tesla currently trades at a trailing price-to-earnings ratio near 326, with a forward price-to-earnings ratio approaching 400. To justify that premium, the market expects Tesla to significantly disrupt the traditional transportation and logistics sectors. Forward earnings projections, which imply growth of about 56%, suggest institutional models are looking past recent earnings misses, including the second-quarter 2026 report, in which Tesla reported earnings of about 33 cents per share versus the 50-cent estimate. The market is aggressively pricing in future cash flows from an autonomous network. We can use Uber Technologies, Inc. (NYSE: UBER) as a benchmark for how the market values legacy ride-share models. Uber operates with a net margin approaching 17% and a return on equity above 43%. Despite these solid fundamentals, Uber trades at a relatively modest trailing price-to-earnings ratio of about 17. The market heavily discounts the long-term durability of traditional ride-share companies, recognizing the existential threat posed by scalable, driverless competitors. While Uber has spent years perfecting the logistics of human-driven fleets, the structural cost of contractor payouts limits long-term margin expansion compared with a fully autonomous network. Incumbents are aware of this dynamic and are positioning themselves defensively. Uber recently launched a supervised autonomous ride-hailing service in London, using Wayve's artificial intelligence technology in a fleet of Ford Mustang Mach-E vehicles. Alongside this rollout, Uber initiated a 10% reduction in its global workforce, eliminating about 3,400 jobs. These actions represent a rapid, sector-wide restructuring aimed at optimizing margins and insulating current operations from emerging automated competitors. Uber's reliance on third-party autonomous partnerships, combined with its headcount reduction, underscores the severity of the threat. Clearing the Intersection: FSD Testing Gains TractionAlthough Tesla's premium forward multiples reflect strong institutional belief in this transition, achieving sustainable fleet revenue remains dependent on operational execution and regulatory frameworks. The transition to a driverless economy is far from complete. Removing traditional controls from a vehicle introduces significant legislative hurdles that have yet to be cleared globally. Scaling an autonomous network requires continued capital investment in artificial intelligence infrastructure, which will pressure free cash flow until the network is fully operational and generating reliable daily fares. There are early signs of regulatory momentum abroad. French regulators recently confirmed on-road testing of full self-driving systems. Documentation submitted for European approval indicates about 195,000 kilometers of testing on French roads without notable incidents. This data suggests that regulatory tailwinds may be forming and could inform a broader European Union approval vote in the future. Progress through European regulatory processes would help validate the safety profile of the underlying software and provide a blueprint for expansion into other highly regulated markets. However, domestic and international legislative hurdles remain the primary bottleneck to scalable fleet monetization. Building fleet-management operations from the ground up requires flawless execution. Tesla must prove that it can handle the granular details of fleet maintenance, charging logistics and customer service at scale. The established logistics networks of legacy ride-share companies provide a functional, revenue-generating bridge to autonomy that pure-play entrants still need to build from scratch. The Final Mile: Capitalizing on the Driverless ShiftThe deployment of autonomous hardware represents a critical juncture for the transportation sector. Transitioning from a hardware-centric manufacturing model to a scalable logistics network offers a path to margin expansion, provided the technology and regulatory approvals align. The market is pricing in a successful transition for autonomous pioneers while applying a heavy discount to traditional ride-share models, forcing industry-wide restructuring and strategic partnerships. The valuation gap between innovators and incumbents reflects a clear expectation of cash flow disruption over the next decade. Investors evaluating this space should monitor the progress of international regulatory approvals and the rollout of these initial autonomous fleets. Cautious investors may prefer to watch how early fleet-utilization metrics affect quarterly cash flows before taking a position, as the premium multiples require nearly flawless execution in the quarters ahead. Observing how traditional platforms adapt their cost structures in response to these emerging networks will also provide critical context for the long-term prospects of legacy ride-share equities. . |


