
| Unsubscribe |
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Hey, take a look at this.
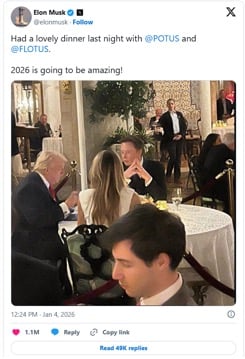
That's Elon Musk having dinner with the President back in January.
Elon posted it himself.
His caption?
"2026 is going to be amazing."
And guess what’s happening now?
>>> Washington is clearing the runway for
Elon’s Biggest Project To Date <<<
- Elon filed a plan with the FCC to quite literally take over the AI industry… From outer space.
- Trump signed an order gutting the red tape around commercial space launches
- He also signed a second order pushing NASA to hand its work to private companies (aka SpaceX)
After thirty years on Wall Street, I can tell you: nothing is a coincidence.
And what Elon's doing in AI is exactly what he's done his entire career.
Take an industry, and make it his.
He took over mobile payments PayPal.
He took over electric cars with Tesla.
And he took over commercial space launches SpaceX.
NOW…
He’s doing it with Artificial Intelligence.
Every single time, people who were positioned early for Elon’s NEXT PROJECT walked away millionaires.
By my estimate, he's already minted over 100,000 of them.
But I believe this one could be his biggest yet.
I believe we could see as many as 1.8 million new "Musk Millionaires”
And there's one company sitting at the dead center of his plan.
It isn't Tesla. It isn't SpaceX.
SPOILER: It’s not even a company Elon owns.
It's a name almost nobody's talking about, and it still trades for less than $100.
I put the whole story into my brand-new FREE Millionaire Maker Masterclass.
When you join I’ll show you exactly what Elon filed…
Why I believe he's the only man alive who can pull it off…
And how to position yourself before September 25th.
[ >>> JOIN MY FREE Millionaire Maker Masterclass NOW <<< ]
Sincerely,
James Altucher
The September Scramble: Find Sanctuary in These 3 Defensive Dividend Stocks
Written by Thomas Hughes. Article Published: 9/17/2026.
Key Points
- Amid rising inflation and interest-rate concerns, investors are gravitating toward defensive dividend stocks that combine strong balance sheets with pricing power.
- Casey's General Stores is diversifying into prepared foods, becoming the fifth-largest domestic pizza chain while maintaining 27 consecutive dividend increases and low debt.
- Johnson & Johnson's pipeline and MedTech repositioning support its Dividend King status, while PepsiCo's GLP-1-driven selloff has created a high-yield opportunity near 4.3%.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
Fed uncertainty, oil prices, and macroeconomic pressures are bringing inflation and interest-rate fears to a head. Investors are fleeing to dividends, and for good reason: Dividends provide steady, reliable income and returns regardless of market volatility.
Defensive dividend stocks are even more appealing. These names are better positioned to withstand higher interest rates and inflation and are especially prized by investors. Regardless of sector or end market, they tend to share several characteristics, including healthy balance sheets, limited debt exposure, and pricing power tied to nondiscretionary products and services.
The REAL Reason Trump is Invading Iran (Ad)
For a moment…
Forget about Trump’s ties to Israel.
Forget about reports of Iran’s nuclear program.
Because my research has led me to believe we’re risking World War 3 with Iran for a completely different reason.
Click here to find out what it is.Their stock prices aren’t immune to market malaise; they can fall alongside the broader market. However, they tend to decline less during downturns and produce market-beating total returns over time, particularly for compounders. Compounding is critical, as dividend reinvestment improves leverage and accelerates annual returns. The best defensive dividend stocks also buy back shares, supporting earnings-per-share growth while giving investors even more leverage.
Casey’s General Stores Is in the Midst of an Inflection
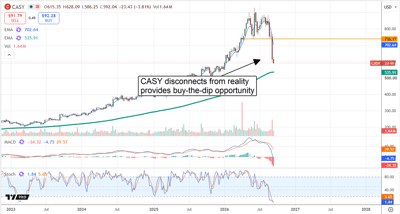
Casey’s General Stores (NASDAQ: CASY) is a poster child for buy-and-hold stocks. The company is consolidating highly fragmented markets, expanding its convenience-store chain organically and through acquisitions, and doing so with very little debt.
Key details include the ability to self-fund growth, pay dividends, and buy back shares. These factors underpin the 2026 thesis, but they aren't the whole story, because the company is in the midst of a major transition.
Casey’s strategy includes inside sales, specifically food and, more specifically, hot prepared items such as sandwiches and pizza. Store-count expansion and the popularity of its pizza have helped make Casey’s the fifth-largest domestic pizza chain, changing its fundamental nature. Casey’s is a convenience store and a gas station, but it is also a restaurant with solid margins, profitability, cash flow, and growth at a time when others are struggling.
Casey’s dividend isn’t substantial in terms of yield—about 0.4% as of mid-September—but it is exceptionally safe and expected to grow at a semi-aggressive pace in the coming years. Casey’s is a Dividend Champion with 27 consecutive increases, a sub-15% payout ratio, and a double-digit distribution growth rate. Share buybacks are also sustainable, reducing the share count incrementally each quarter. The biggest risks are expectations for additional acquisitions and the possibility that management will suspend buybacks to help cover the costs.
Johnson & Johnson, a King Among Dividend Payers
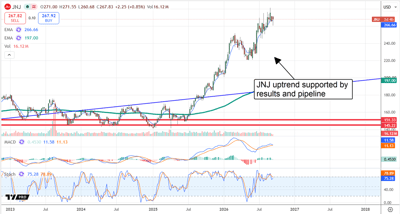
Johnson & Johnson (NYSE: JNJ) stock has risen in 2026 due to a combination of factors, from Kenvue’s spinoff to its strong pipeline.
The firm is repositioning around Innovative Medicine and MedTech, improving margins and accelerating sales of key therapies.
For investors, this means sustained cash flow, capacity for dividends, and the likelihood that semi-aggressive distribution increases will continue. Johnson & Johnson is a Dividend King with more than 60 consecutive increases and a payout ratio of about 60% of earnings. Earnings are expected to grow at a modest double-digit pace over the next five years.
The growth outlook has analysts bullish, underpinning the stock price action and the market advance.
While consensus assumes fair value near the late-summer highs, positive trends support the high end of the range and the potential for fresh all-time highs. Catalysts include FDA approval of Icotyde and Imaavy, as well as positive trial results for several compounds treating blood cancers.
Dividend King PepsiCo Down on GLP-1 Inhibitors
PepsiCo (NASDAQ: PEP) shares are suffering from GLP-1 shock, with consumers snacking less than before.
The caveat is that PepsiCo is a well-established consumer giant, the largest staples company in the market, and well positioned to pivot. Efforts are already underway to realign with snacking trends, including protein-enhanced products designed to meet the needs of GLP-1 users and reflect modern health trends.
The market gets this company wrong because underlying metrics reveal slow, steady improvements, with strengths in key areas such as international markets.
Key details: 2026 results are sufficient to sustain financial health, pay dividends, buy back shares, and invest in growth.
PepsiCo uses debt as part of its strategy but mitigates this with its strong balance sheet. Most of its debt is at fixed rates and is unaffected by rate increases.
PepsiCo’s dividend is very attractive. The 2026 price weakness created a deep-value, high-yield opportunity, with PEP at the low end of its historical valuation range and the high end of its yield range. Trading at a mid-teens price multiple, PepsiCo’s stock price could rise about 65% on valuation alone while paying a 4.3% dividend yield.
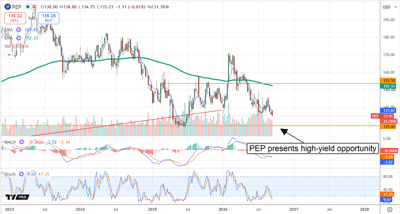
Buybacks aren’t robust, but they reduce the share count quarterly, aiding earnings-per-share growth. PepsiCo’s risks include rising commodity costs, including PET resin, a critical bottling component. To address this, PepsiCo, in line with Elliott Management’s recommendations, is cutting costs, rationalizing stock-keeping units (SKUs), and investing in AI efficiencies.
Blue-Chip Stocks Are Looking Anything But Boring With Dividends and Big 2026 Gains
Submitted by Chris Markoch. Posted: 9/14/2026.
Key Points
- Coca-Cola has outperformed the broader market in 2026 while extending its dividend-growth streak to 64 consecutive years.
- Chevron has benefited from strong energy markets, record production, and the integration of Hess while continuing to raise its dividend.
- Merck has rallied sharply as Keytruda remains a powerful earnings driver and its oncology pipeline offers potential growth beyond the drug’s approaching patent cliff.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
Investors who believe that blue-chip stocks are boring haven’t been paying close attention in 2026. This year, several stocks that have often lagged the S&P 500 are having stellar years, rewarding buy-and-hold investors.
To be fair, growth-hungry investors often overlook blue-chip stocks for practical reasons. These are older companies at a mature stage in their business cycles, with solid balance sheets that provide predictable gains for investors. However, predictability can also limit the kind of upside growth investors typically chase.
The Massive Cost Hiding Behind the AI Boom (Ad)
The AI boom needs massive amounts of electricity, and someone has to pay for the new power infrastructure that supports it.
The House just voted 417-3 to pass a bill aimed at protecting ordinary Americans from those costs. One Weiss Ratings analyst warns rising electricity bills are just one of four major threats the AI boom poses to your finances.
See the full breakdown of AI's economic risks hereWhy has the script flipped for several blue-chip stocks in 2026? Some of it is sector rotation as investors look for gains outside of the artificial intelligence (AI) trade. Energy and biotechnology have been among the sectors attracting investor interest. But even some consumer-facing stocks are performing well.
Stock price returns are only one part of the story. Each of these stocks offers an attractive and growing dividend. Together, those dividends and share-price gains can support long-term compounding.
Coca-Cola Stock Delivers Strong Returns and a Growing Dividend
The Coca-Cola Co. (NYSE: KO) is a blue-chip stock that’s been made iconic by legendary investor Warren Buffett, who is famously associated with the company and has often spoken about drinking Coca-Cola. Buffett appears to like the product almost as much as he likes the company. Coca-Cola has been a staple in the portfolio of Berkshire Hathaway (NYSE: BRK.B) for decades.
The attributes that attracted Buffett to KO remain in place today. The company has a strong brand; it delivers consistent growth and a growing dividend.
Over the last 10 years, KO has delivered a total return of around 177%, including reinvested dividends. In 2026, the stock has also outperformed the S&P 500, with shares up about 25% through early September before dividends.
Coca-Cola is a Dividend King, having increased its dividend for 64 consecutive years. Its dividend currently yields 2.41%, with a payout of $2.12 per share annually.
Coca-Cola has a more diversified portfolio in 2026 than it did when Berkshire first bought the stock. That’s one reason the company raised its full-year outlook despite lingering concerns about the health of lower-income consumers and the impact of GLP-1 drugs on the company’s core soft-drink business.
Chevron Stock Rides Energy Tailwinds and a Growing Dividend
Many energy stocks, particularly those in the oil and gas industry, have been outperforming the S&P 500 in 2026. One of the best examples is Chevron Corp. (NYSE: CVX). The integrated oil company has tailwinds from its existing portfolio, which is heavily concentrated in the Permian Basin, along with the benefits of integrating its completed merger with Hess.
The company also has an established presence in Venezuela, where it recently expanded its position and outlined plans for additional investment and production growth.
Critics may argue that Chevron, like many oil stocks, is enjoying a cyclical tailwind fueled by geopolitical events. But that’s only part of the story. The current infrastructure buildout in the United States will span the rest of this decade and likely beyond. And while renewables may be the future, oil is still very much part of the present.
Like Coca-Cola, Chevron is part of the Berkshire Hathaway portfolio. One reason is the company’s growing dividend and commitment to share buybacks. The company is a Dividend Aristocrat, having increased its dividend for 38 consecutive years. In addition to an attractive 3.34% yield, Chevron pays $7.12 per share annually.
CVX is up nearly 40% in 2026, more than three times the S&P 500’s gain through early September. Including dividends, the stock’s total return is even stronger.
Merck Stock Benefits From Oncology Growth and a Strong Pipeline
Merck & Co. (NYSE: MRK) rounds out this group of blue-chip stocks that have outperformed the S&P 500 in 2026. The company is best known for its blockbuster oncology drug, Keytruda.
It’s hard to overstate the impact of Keytruda on Merck’s financials. The drug, which is approved for several types of cancer across 44 indications and 19 tumor types, accounts for more than 55% of the company’s pharmaceutical sales.
That's why investors are eyeing the company’s strategy for managing the patent cliff for Keytruda, which begins for some indications in 2028. One reason for optimism is the company’s deep pipeline.
That includes the drug it’s developing with Moderna (NASDAQ: MRNA), which delivered positive top-line data in a Phase 3 study in August. This will help position Merck in the emerging field of personalized medicine, particularly in oncology.
MRK is up over 40% in 2026, with dividends pushing its total return above that level to over 43%. The company’s dividend yields 2.35% and pays $3.40 per share annually. Merck has increased that dividend for 14 consecutive years.
This email communication is a paid sponsorship for Paradigm Press, a third-party advertiser of InsiderTrades.com and MarketBeat.
If you have questions or concerns about your account, feel free to email our South Dakota based support team at contact@marketbeat.com.
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Pl., Sixth Floor, Sioux Falls, South Dakota 57103-7078. United States..
