 A Message From Brownstone Research Editor’s Note: Jeff Brown is the former tech executive who picked Nvidia in 2016 before it jumped 37,000% higher. He’s now recommending another AI stock that’s the same size Nvidia was 10 years ago. He calls it “Elon Musk’s One Stock Retirement Plan” because he believes Elon Musk is about to create massive demand for this company’s patented technology. Click here to see the details or read more below.
Dear Reader, Sometimes you come across an opportunity so explosive… That it has the potential to turn a small stake… Into a six figure and in some rare cases even a seven-figure nest egg… Like it happened when I picked Nvidia in 2016. It jumped high enough to turn $5,000 into an entire retirement nest egg of $1,895,000. And while I can’t guarantee you’ll become a millionaire... I think this little-known AI stock is one of those opportunities… Which is why I call it “Elon Musk’s One Stock Retirement Plan.” Now, if this idea of retiring with a single stock sounds crazy to you… You should know that some of the best investors in the world believe that the idea of diversification is a little overrated. Stanley Druckenmiller said… “You don’t get rich by diversifying into 50 mediocre assets. You get rich by finding two or three asymmetric home runs.” I believe this stock is an asymmetric home run. Or listen to legendary investor Peter Lynch. He said… “I would own one stock if I can find one great stock.” Even Warren Buffett said… “Diversification is protection against ignorance. It makes little sense if you know what you are doing.” Click here now and I’ll show you why I believe this stock might be the only one you need to retire. Jeff Brown,
Founder & CEO, Brownstone Research P.S. If I could buy only one stock, this would be it… it might just be the perfect tech stock. It’s a leader in an AI breakthrough that’s protected by 150 patents… It’s a small company, unknown to most people… still in the initial phase of exponential growth… Plus, it has a near term catalyst that could send shares skyrocketing… starting November 11.
Further Reading from MarketBeat.com
Cleared for Takeoff: AAR Corp. Expands Its Aerospace Aftermarket ReachWritten by Jeffrey Neal Johnson. Posted: 10/1/2026. 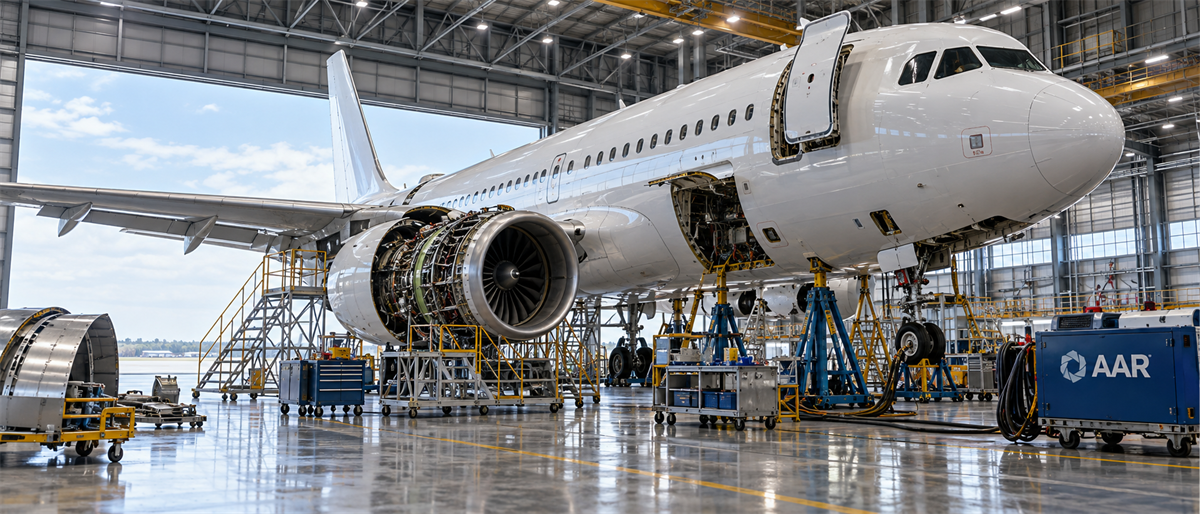
Key Points
- Persistent aircraft delivery constraints are extending fleet life cycles and supporting demand for aviation maintenance, parts and repair services.
- AAR’s acquisition of MRO Holdings significantly expands its exposure to higher-margin heavy aircraft maintenance.
- Investors will be watching margin expansion and leverage reduction to determine whether the acquisition can justify the added debt and dilution.
- Special Report: Porter flew 3,300 miles to investigate this system
The commercial aviation industry faces a persistent supply chain bottleneck. With major original equipment manufacturers struggling to meet delivery schedules for new aircraft, airlines have few options but to extend the life cycles of their existing fleets. This dynamic shifts capital expenditure away from new aircraft purchases and directly into heavy maintenance, repair and overhaul services. Companies positioned to service these aging fleets are benefiting from a structural tailwind that shows little sign of abating. AAR Corp. (NYSE: AIR) is strategically consolidating this market, turning a macroeconomic pain point for airlines into an accretive growth engine for its aftermarket platform. Cruising Altitude: A Baseline of Growth
Before examining the recent multibillion-dollar acquisition, it is important to understand AAR Corp.'s baseline operational health. AAR Corp.'s first-quarter fiscal year 2027 results highlight a business already operating with significant momentum. Revenue reached about $918 million, up roughly 24% year over year and well above consensus estimates. Adjusted earnings per share came in at approximately $1.49, beating expectations by a comfortable margin. This growth was largely driven by a roughly 28% increase in commercial sales, alongside 23% organic growth in new-parts distribution. Original equipment manufacturers such as Boeing (NYSE: BA) and Airbus (OTCMKTS: EADSF) are navigating severe production constraints that are delaying new-aircraft deliveries by years. When airlines keep older planes in service longer, they require a steady stream of replacement parts and specialized technical services to maintain regulatory compliance and safety standards. This reality is reflected in AAR Corp.'s profitability metrics, with adjusted EBITDA growing approximately 34% to about $117 million for the quarter. These results demonstrate management's ability to execute in its core segments and efficiently capture the increased maintenance spending flowing through the aerospace sector. With a trailing price-to-earnings ratio near 21.5 and a forward price-to-earnings ratio of about 17.7, AAR Corp. presents an interesting valuation framework even before the new assets are fully integrated. Upgrading the Fleet: Heavy Maintenance, Heavy MarginsBuilding on this organic growth, AAR Corp. recently entered a definitive agreement to acquire a 65% controlling stake in MRO Holdings. The transaction carries an implied enterprise value of about $4 billion, with the initial equity stake valued at $1.8 billion. AAR Corp. retains the option to acquire the remaining 35% within a six-year window, allowing for a phased approach to full ownership. The strategic value of this acquisition lies in its immediate and long-term impact on profitability. Heavy maintenance requires specialized hangars, certified labor and extensive regulatory approvals. By consolidating this fragmented market, AAR Corp. gains greater scale and pricing power. AAR Corp.'s standalone adjusted EBITDA margin for the first quarter was approximately 12.7%. In contrast, MRO Holdings operates with a 27% margin profile. This high-margin generation stems from specialized airframe maintenance capacity across the Americas and deep, long-term relationships with premier airline customers. MRO Holdings is projected to generate about $285 million in adjusted EBITDA on estimated calendar-year 2026 revenue of $1.0 billion. By consolidating these operations, AAR Corp. projects a clear path toward consolidated adjusted EBITDA margins of approximately 19% to 20% over the next 36 to 48 months. Following the deal, AAR Corp. will become the largest heavy-maintenance provider globally, servicing approximately 3,000 aircraft annually. Management has identified $75 million in run-rate cost efficiencies to support the integration, primarily through operational optimization, procurement savings and shared best practices. For investors evaluating the long-term potential, this acquisition represents a fundamental shift in AAR Corp.'s valuation profile by structurally lifting its margin ceiling. Pricing in the Baggage: Debt and DilutionDespite the clear long-term margin accretion, the broader market reacted poorly to the announcement. AAR Corp. shares fell about 22% over the past month, punctuated by a 7% gap down after the acquisition news. Research desks downgraded AAR Corp., citing balance sheet risks and execution hurdles tied to the transaction. Funding a deal of this magnitude requires $2.1 billion in new debt, pushing net leverage to a peak of about 3.6 times at closing. Issuing roughly $780 million in equity creates near-term shareholder dilution. In a high-interest-rate environment, carrying $2.1 billion in debt is a legitimate concern for investors. The market is currently pricing in the immediate cost of the transaction while heavily discounting its potential future operational benefits. A closer look at the deal mechanics reveals a more nuanced risk profile that may not be fully reflected in recent price action. First, existing MRO Holdings shareholders accepted $780 million in AAR Corp. stock priced at $135 per share. This represents roughly a 30% premium to current trading levels and aligns the sellers' financial interests with the successful integration of the two operations. Second, AAR Corp. negotiated a deleveraging covenant that allows the business to capture 100% of MRO Holdings' excess cash flow during the first two years of ownership. Because MRO Holdings converts approximately 70% of its adjusted EBITDA into cash flow, this aggressive cash flow sweep mechanism is designed to rapidly reduce the impact of its 3.6-times peak leverage. Management expects to reduce leverage to around 3 times within two years and return to a target range of 2 to 2.5 times over the medium term. Blue-chip institutional investors also validated the deal structure by leading an estimated $230 million private investment in a public equity offering. Capturing the Aerospace AftermarketThe current share price weakness reflects a market heavily focused on near-term balance sheet expansion and equity dilution. Yet the underlying mechanics of the MRO Holdings acquisition address these concerns through the cash flow sweep structure and aligned seller incentives. The aerospace supply chain continues to force airlines into extended fleet-maintenance cycles, providing a durable macroeconomic tailwind for AAR Corp.'s expanded service capacity. Planes must be serviced to fly, and AAR Corp. has secured a strong position in this necessary segment of the aviation market. As AAR Corp. integrates this acquisition, it is positioning itself to capture a larger share of the higher-margin commercial aviation aftermarket. Investors evaluating industrial equities may want to add AAR Corp. to their watchlists and monitor how the business executes on its projected margin expansion in the coming quarters. . |


