|
Sponsored content from Golden Portfolio
Right now, you can buy a dollar's worth of gold for about 36 cents. That sounds impossible. Here's how it's real. The major gold miners are throwing off record cash flow — even after gold's recent pullback. The four largest have never had this much free cash on hand. Ever. At today's gold price, they're running margins as high as 75% — the most profitable they have ever been. Which hands them a problem. Go here to see the problem — and why the majors are about to go on a shopping spree for the ages. When a major gold miner makes record profits, it does one of two things: hand the cash back to shareholders, or buy the best junior mining assets to secure future production. And here's the piece the market is missing: The best junior assets are still priced as if gold were stuck at $1,800 an ounce — not north of $4,000, where it trades today. So the majors are staring at their own future production shrinking, sitting on record cash, looking at top-tier junior assets trading at a fraction of what that gold is worth at today's price. They don't have a choice. They buy — or their output keeps shrinking until they're out of business. That's how you buy a dollar of gold for 36 cents: you own the junior before the major is forced to pay up for it. The gap between what these assets are worth and what they trade for has a name. I call it the Golden Anomaly. It only appears early in a gold bull market, and it closes fast — usually the moment the majors start writing cheques. So you can pay full price after the gap closes… Or buy the dollar for 36 cents while the Anomaly still exists. My name is Garrett Goggin, CFA, CMT, and it's why Porter Stansberry recently called me: "THE most knowledgeable gold investor in the world." Go here to see my Golden Anomaly portfolio — and the three names next on the majors' shopping list. Best, Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio
More Reading from MarketBeat
Saddle Up: Texas Stock Exchange Ropes In $80 Billion in ListingsSubmitted by Jeffrey Neal Johnson. Posted: 10/2/2026. 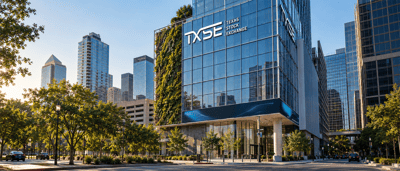
Key Points
- The Texas Stock Exchange begins its corporate listings rollout in October, challenging the New York Stock Exchange and Nasdaq's longtime dominance.
- Energy Transfer, Dillard's, and Texas Capital Bancshares are moving roughly $84 billion in combined market capitalization to the TXSE, citing lower fees and reduced friction.
- Backed by Citadel Securities and BlackRock with about $430 million in capital, the TXSE's real test will be attracting large-caps without Texas ties.
- Special Report: This AI fund sends investors payouts every Thursday

For decades, the New York Stock Exchange and Nasdaq (NASDAQ: NDAQ) have dominated U.S. corporate listings. That dynamic faces a structural test this October as the Texas Stock Exchange (TXSE) begins rolling out corporate listings. The TXSE itself already launched live trading in July, followed by its first exchange-traded product (ETP) listings in September. Backed by institutional heavyweights, the Dallas-based upstart is actively courting established companies away from legacy platforms. Attracting multi-billion-dollar primary listings from Energy Transfer (NYSE: ET), Dillard's (NYSE: DDS), and Texas Capital Bancshares (NASDAQ: TCBI) gives investors a real-world look at whether optimized issuer economics and regional ties can permanently disrupt U.S. capital markets. This migration signals a potential shift in how public corporations manage their capital-market footprints. Building the New Frontier: The Mechanics of the TXSE
Elon Musk recently described a new class of technology using three words: Infinite. Money. Glitch.
James Altucher has put together a presentation explaining what this technology is and why he believes it could be a major market event. Viewers who watch before October 21 can also claim a free report detailing Musk's trillion-dollar compensation package and the companies tied to his incentive targets. Watch the presentation before October 21 to learn more.
The TXSE closed a funding round in September 2026, bringing its total capitalization to approximately $430 million. This capital pool is critical because it helps secure the high-frequency market-making infrastructure required to handle large-cap trading volume. With Citadel Securities and BlackRock (NYSE: BLK) providing key infrastructure, the TXSE is addressing historic concerns that regional exchanges may lack the liquidity needed to support major corporate equities. The exchange's value proposition for issuers centers heavily on economics. Corporate boards constantly evaluate compliance costs and exchange fees, which can erode cash flow over time. The TXSE promises a technology-driven framework designed to reduce operational friction and lower the cost of maintaining a public listing. By fostering a transparent, dedicated third alternative, exchange leadership aims to encourage more competitive pricing across national listings. Pioneers of the Plains: Energy and Retail Head SouthThe October migration of Energy Transfer and Dillard's establishes an approximately $80 billion beachhead for the Dallas platform. Both companies maintain deep geographic ties to Texas, but the underlying drivers behind their moves offer a more nuanced look at capital efficiency and margin protection. Energy Transfer Lowers Overhead CostsEnergy Transfer targets a leverage ratio of 4x to 4.5x EBITDA and has a market capitalization of about $68 billion. Managing that balance sheet requires highly efficient capital markets to roll maturities forward and fund ongoing infrastructure projects without penalizing equity holders. Energy Transfer currently supports a forward distribution yield of about 6.8%, and any reduction in corporate overhead directly helps support that high-yield payout structure. Energy Transfer is transitioning its common units alongside its Series I preferred units. Moving complex, multi-tiered capital structures demonstrates the TXSE's ability to support instruments beyond a standard common-stock listing. Insider activity suggests management sees clear value in the transition. Corporate directors accumulated more than one million shares in recent months, deploying about $21.5 million in capital. While founder Kelcy Warren is an early investor in the TXSE, the broader strategic value lies in accessing an additional capital-market venue as Energy Transfer navigates fluctuating commodity cycles. Shares declined approximately 5.5% over the trailing 30 days amid broader energy volatility, making cost-saving structural moves timely. Dillard's Hedges Retail Margins in the Lone Star StateRetail operates on tight margins, and Dillard's faces sustained macroeconomic pressures. Rising global tariffs have directly affected the cost of goods sold across the department-store sector, squeezing profitability from the top down. With a trailing price-to-earnings ratio near 15x, above the peer average, Dillard's management is actively searching for ways to defend bottom-line profitability against these structural headwinds. Dillard's reincorporated in Texas in 2025 and operates its largest retail footprint in the state. Leveraging the TXSE's promised reduction in listing fees could help offset broader margin compression. By transitioning its Class A shares and capital trust securities, Dillard's essentially turns administrative cost savings into a direct defense of its operating margins. Price action has remained choppy and range-bound recently, with the stock peaking near $688 before retracing. Locking in lower structural costs provides a tangible financial benefit while consumer discretionary spending remains under pressure. Banking on the Home Turf: A Regional Player Scales UpThe financial sector is represented by Texas Capital Bancshares. The regional bank is shifting its primary corporate listing and exchange-traded funds away from Nasdaq. Texas Capital Bancshares effectively stress-tested the TXSE's clearing and routing mechanics in mid-September by transferring two ETFs to the platform as part of the exchange's broader ETP listing launch. This strategy aligns with the fundamental restructuring underway at Texas Capital Bancshares. Trading at a trailing price-to-earnings ratio of 12.4x, the bank is rapidly scaling its investment banking and advisory unit. Management is deliberately pivoting away from traditional net interest income toward capital-efficient, fee-based revenue streams. Transitioning to the TXSE positions Texas Capital Bancshares to underwrite, advise and provide treasury services for future corporate clients looking to migrate to the new exchange. Institutional investors appear to support the strategy. Filings show BlackRock taking a new equity stake of around 12.8%, valued at about $578 million, alongside fresh long positions from Deutsche Bank and CIBC. Insider activity reflects strategic liquidity events, notably a liquidation of about $5 million by the CEO earlier in the summer, which institutional demand readily absorbed. High Noon for Legacy Exchanges: The Real Test AheadSecuring approximately $80 billion in combined market capitalization across these three entities validates the TXSE as a potentially viable liquidity hub. The institutional backing and successful transfer of complex financial instruments suggest that the exchange possesses the technical capacity to host large-cap equities from day one. Early adoption currently relies heavily on geographic and advisory alignment. Energy Transfer, Dillard's and Texas Capital Bancshares all share strategic ties to Texas. The true measure of the TXSE's competitive viability against the New York Stock Exchange and Nasdaq will depend on its ability to secure primary listings from corporate boards without geographic ties to Dallas. If the platform can attract non-affiliated large-cap companies in upcoming quarters by relying on superior issuer economics and reduced regulatory friction, the U.S. capital markets may face a genuine paradigm shift. Investors may want to monitor the bid-ask spreads and daily trading volumes of these three early adopters throughout October. A seamless transition with sustained liquidity could pave the way for a broader corporate exodus, signaling an opportune time to evaluate the competitive positioning of legacy exchange operators. |