
| Unsubscribe |
Dear Fellow Investor,
If you're tired of the endless market swings and looking for a way to generate consistent income, then stop everything you're doing and read this.
Your FREE copy of “The Money Press Method: How to Generate Consistent Income Using Weekly Options” is ready to ship (US customers only).
The Money Press Method is kinda like creating little AirBnB rental properties in the stock market that create weekly rent checks
Simply visit this page, and enter your details to claim your complimentary copy PLUS the complete Money Press Method tutorial bundle, FREE. (limited time)
Throughout the course of this comprehensive, 100-page book, you’ll learn everything from the basics of options to one of the most powerful strategies on the planet, the Money Press Method.
Here’s a glimpse of what you’ll get when you act today:
✔ INSTANT Digital Access to the Money Press Method before your book arrives
✔ Physical Copy of the guidebook rushed directly to your doorstep
✔ 2 Bonus Quick-Start Training Videos, including the Money Press Method strategy training, and the popular...
✔ "How To Get Started On $10,000 or Less" training
✔ Our highly-praised “Money Press On-Ramp” to get you profiting in as little as a few days
Normally this bundle retails for $79.00. But not today.
Once you have the Money Press Method in hand, you’ll immediately discover these timely benefits:
- Weekly income potential (the Money Press gives you this while carefully managing risk)
- Because it's a "market-neutral" strategy, the Money Press works under any set of market conditions, including NOW…
- Minimal Time Commitment: trades can be executed in approx. 30 minutes each week
- Sleep-At-Night protection is built right in - no more nervous checking your account day and night
- Small account OK! Trade the world's top stocks (even if they're $600, $700, or more) with accounts less than $10,000
And that's just scratching the surface.
What People Are Saying About
The Money Press Method
“I never thought I'd see the day, but last Thursday my account was up $150K in a single day! Compared to every other program I've tried, your methods rock! Keep those good trades coming!” - Jeff S., NC
“Thank you and your team for what you do. I've tried lots of investing and trading approaches and nothing compares with your methods.” - Sunil M., CA
“I have been sucked in by other programs and have not made a penny. You are the ONLY person I want to follow and have been for the last 2 years. Please keep up the GREAT work.” - J. Hurrell, FL
Remember, this offer is only available while supplies last. Claim your FREE book and tutorial bundle before it's too late.
Claim Your FREE Book & Tutorial Bundle Bonuses Now!
Don't miss out on this life-changing opportunity. Secure your copy and start your journey to consistent weekly income today.
To your success,
Preston James
Traders Edge Network
L3Harris Stock Took a Beating—Is a 20% Rebound Next?
Authored by Thomas Hughes. Published: 11/1/2026.
Key Points
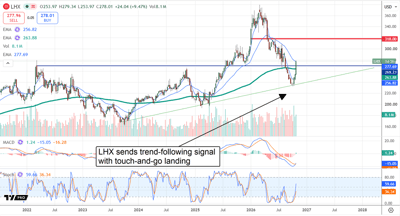
- L3Harris Technologies shares show a bullish trend-following signal after a 2026 correction, with technical indicators pointing to resistance tests near $300 to $320 within 12 months.
- The company reported strong Q3 results, with revenue up 7% to $6.1 billion and earnings per share of $3.28, both beating analyst consensus estimates significantly.
- Analysts maintained a roughly 25% upside consensus price target after Q3 earnings, supported by raised 2026 guidance, record backlog, and continued capital returns to shareholders.
- Special Report: The Last Energy Revolution Starts Now
Despite its steep 2026 correction, L3Harris Technologies' (NYSE: LHX) stock price uptrend remains intact, as recent price action shows.
Backed by a solid earnings report, LHX touched down on an existing trend line, produced a strong trend-following signal, and offered an entry point with high double-digit to triple-digit return potential.
Today's stock pick is on me (Ad)
Elon can't build his satellite network without one key supplier, and he's paid this company since 2012.
His plan for 1,000,000 satellites could multiply that bill significantly, putting this overlooked stock back in focus.
Dylan has circled December 8th as a key date for this pick.
Claim today's free stock pick before December 8thThe stochastic and MACD indicators support this outlook. Both show bullish crossovers near the bottom of their ranges, aligning with the trend-following move and suggesting ample room for the stock to run. In this scenario, the next major hurdles are technical resistance in the $300 to $320 range and, beyond that, the existing highs, which are likely to be tested within the next 12 months.
L3Harris Q3 Earnings Beat and Record Backlog Strengthen the Bull Case
Analyst trends are closely tied to LHX’s stock price action. Midyear price target reductions weighed on market sentiment, but that trend is ending.
Initial analyst responses to L3Harris's Q3 results included cautious commentary on execution hurdles but no price target cuts. Ratings were reaffirmed, helping stabilize the consensus price target.
Although down from its peak, the consensus forecast pointed to more than 20% upside as of late October, supported by coverage from a sufficient number of analysts.
LHX’s Q3 results were strong, revealing broad-based strength, segment-specific strength in Space & Mission Systems, and scale-driven leverage in earnings and cash flow. Revenue grew 7% to $6.1 billion, beating consensus by 270 basis points (bps). Growth was driven by a 10.3% gain in Space and Mission Systems, a 3.1% gain in Communications and Spectrum Dominance, and a 4.9% increase in Missile Solutions.
Margins were another strength. The company posted a 200-basis-point improvement in GAAP operating margin, driving a 26.6% increase in operating income and comparable strength at the bottom line. Earnings per share of $3.28 beat estimates by more than 1,000 bps and grew more than 30% year over year (YOY) to a quarterly record. More importantly, cash flow was strong at $1.4 billion, nearly 23% of revenue, while free cash flow (FCF) reached $1.26 billion, driving 195% YOY FCF growth.
Guidance was strong and may be cautious, given the underlying results and ongoing global conflicts. Management raised its revenue and earnings targets, with a particularly large increase to its earnings outlook, putting both above consensus forecasts. For full-year 2026, L3Harris now expects earnings of $12.25 to $12.35 per share, with even the low end exceeding analysts’ $11.90 consensus estimate.
Reasons to believe the guidance may be cautious include $19.3 billion in new orders, a record backlog, and a 3.2-to-1 book-to-bill ratio. This metric indicates that new orders are coming in more than three times as fast as existing orders are being filled.
Capital Returns Provide Lift to LHX Shares
LHX share buybacks have slowed amid government scrutiny but have not stopped, while the company’s capacity to repurchase shares has improved. Q3 buybacks helped reduce the share count marginally over the trailing 12 months, and the company returned about 24% of quarterly free cash flow to shareholders through dividends and share repurchases.
Cash, current assets, and total assets all grew during the quarter, while liabilities increased at a slower pace, boosting shareholders’ equity and strengthening the balance sheet. The company also pays a quarterly dividend of $1.25 per share, or $5 annually, providing an additional source of shareholder returns.
Institutions played a role in LHX’s stock price correction and now underpin its upswing. The group owns about 85% of the shares, giving it an outsized impact on the share price. Institutions were net sellers in Q1 and Q2 as the share price corrected, then returned to a bullish posture in Q3 and early Q4 ahead of the results release. They may continue to provide support and buy dips, but they could also cap upside and sell into rallies as the stock approaches resistance at $300, $320, and $360.
The market misjudged LHX’s near-term headwinds: they do not reflect structural decay or a business implosion, but rather growing pains that could lead to improved results. The market has started to get the pipeline and backlog right, as clear Q3 strength demonstrates.
Q3 strength points to sustained growth, acceleration, and cash flow to fuel capital returns. Upcoming catalysts include the potential spin-off of non-core assets gained through acquisitions. These transactions could reduce the balance sheet’s burden, generate cash, and allow management to focus on growth pillars, including space and next-generation defense applications.
Valuation and short selling are not concerns right now. With earnings improving and backlogs swelling, LHX may still offer upside as its recovery gains momentum. Short sellers may have been blamed for the correction, but MarketBeat data shows low single-digit short interest, insufficient to affect price action.
Alphabet’s $400 Billion Sell-Off Could Be the Best AI Buying Window Left in 2026
Authored by Bridget Bennett. Published: 11/2/2026.
Key Points
- Alphabet’s $400 billion-plus single-session sell-off was driven by advertising misses and non-cash accounting charges, not by any slowdown in its AI business.
- Altimetry Research’s Joel Litman and Rob Spivey see the buildout’s real profit pools sitting with hyperscalers and power suppliers, naming Microsoft, Generac Holdings, and Advanced Micro Devices as the names positioned to capture them.
- CoreWeave and Cipher Digital occupy the squeezed middle of the AI value chain, renting commodity compute without the pricing power or scale to earn their cost of capital.
- Special Report: The Last Energy Revolution Starts Now
Investors just sold off a company for investing in the one business that doubled.
Alphabet Inc. (NASDAQ: GOOGL) fell 12% after its third-quarter report, erasing more than $400 billion in market value. Google Cloud revenue grew 103% in the same quarter.
Today's stock pick is on me (Ad)
Elon can't build his satellite network without one key supplier, and he's paid this company since 2012.
His plan for 1,000,000 satellites could multiply that bill significantly, putting this overlooked stock back in focus.
Dylan has circled December 8th as a key date for this pick.
Claim today's free stock pick before December 8thThat’s the tension worth sitting with: The gap between the market’s reaction and what the numbers showed is where the opportunity lies.
What Alphabet’s 12% Sell-Off Actually Priced In
The two misses that triggered the selling came from Google Search advertising and YouTube ad revenue. Search ad revenue still grew 12% to $63.3 billion.
That is not a franchise being erased by chatbots. It is a franchise growing slightly more slowly than the sell-side had modeled.
Joel Litman and Rob Spivey of Altimetry Research argue that the cloud line invalidates the bubble narrative behind the sell-off.
Demand for AI compute is not softening. Customers are spending more with Google, not less.
The Accounting Rules That Punish Companies for Investing
Alphabet booked an $8.2 billion loss in other income and expenses, driven largely by an unrealized mark-to-market loss on its stake in SpaceX (NASDAQ: SPCX). No cash left the building. Litman points out that these are precisely the rules Warren Buffett has criticized for manufacturing volatility without conveying useful information.
Research and development compounds the distortion. In the United States, R&D hits the income statement as a period expense rather than a capitalized asset, so the companies investing the most can look the least profitable.
Then there is free cash flow, the number that spooked the market most. Alphabet’s free cash flow turned negative because capital expenditures (CapEx) climbed toward a guided $195 billion to $205 billion for the year, not because operating cash flow deteriorated. Litman and Spivey read that as a company with high incremental returns pressing its advantage.
Microsoft’s Azure Capacity Still Sets the Revenue Ceiling
Microsoft Corporation (NASDAQ: MSFT) is following the same playbook.
Chief Executive Officer Satya Nadella has said repeatedly that more Azure capacity would mean more Azure revenue, and each capacity expansion that spooked investors has been followed by a cloud revenue beat.
The recent voluntary exit offer extended to roughly 60,000 employees reads as a sign of distress to much of the financial press.
Spivey reads it as leverage. Headcount makes up an unusually large share of Microsoft’s cost base, and more revenue per employee translates directly into a return-on-investment lift that the market has not priced in.
Generac’s Commercial Power Business Lands in the Right Lane
Generac Holdings Inc. (NYSE: GNRC) is a name nobody files under AI. Spivey argues it belongs there. The residential standby business remains dominant, while the commercial segment, historically the lower-margin half of the business, is finally gaining pricing power as Caterpillar Inc. (NYSE: CAT) builds a backlog that stretches years into the future.
Generac added capacity ahead of that squeeze and has built a data center backlog measured in billions.
Spivey’s view is that reported metrics badly understate the economics, showing low-single-digit returns where Altimetry’s adjusted figures show mid-teens returns and rising. The stock’s slide since its summer peak, he says, reflects the narrative, not the fundamentals.
AMD Gets 2 Shots at the Buildout
Advanced Micro Devices, Inc. (NASDAQ: AMD) benefits from a simple realization spreading through data centers: Not every workload needs NVIDIA Corporation’s (NASDAQ: NVDA) top-end silicon.
Inference is pushing work back toward CPUs, and AMD is the only major designer operating on both sides of that split, with integration between them.
The market has priced in the share-gain story.
It has not priced in the CPU density story.
Why CoreWeave and Cipher Digital Sit in the Wrong Spot
CoreWeave, Inc. (NASDAQ: CRWV) pays top dollar for chips, owns no frontier model and cannot tell customers they have nowhere else to go. Litman’s calculation is blunt: Economic profit is negative today and forecast to stay negative. Cipher Digital Inc. (NASDAQ: CIFR), formerly Cipher Mining, inherits the same problem with a rebrand attached. Renting bare compute is a business Equinix, Inc. (NASDAQ: EQIX) and Digital Realty Trust, Inc. (NYSE: DLR) have run for decades, earning returns on assets of 3% to 4%.
The exception is scale paired with power already in the ground, which is why Spivey points to SpaceX and its xAI operation as the only neocloud he considers genuinely differentiated.
Owning something the buildout can’t route around is the whole game. Cloud revenue and power capacity tell you who qualifies, and five of those names are already cutting checks to shareholders while spending continues. See Joel Litman and Robert Spivey’s 5 AI build-out income stocks in Elon’s Shadow Trust.
This email message is a sponsored message sent on behalf of Traders Edge Network, a third-party advertiser of MarketBeat. Why did I receive this email?.
If you have questions about your subscription, please don't hesitate to contact our support team, based in the United States, at contact@marketbeat.com.
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Pl., Suite 620, Sioux Falls, South Dakota 57103-7078. U.S.A..
