
A Message From Behind the Markets
Fellow Investor,
Yesterday, the deadline hit.
The biggest energy deadline in American history...
And it's now aimed its full firepower at ONE company.
If you missed it, you're not too late.
Yet.
See, on July 4th, the One Big Beautiful Bill Act killed the federal tax credits that powered alternative energy for years.
But here's what almost nobody knows:
When the White House killed credits for solar, wind, EVs, and every other renewable energy source in America…
They left one untouched.
Not only that - they reclassified it alongside oil and nuclear...
And gave it eight years of credits.
Because in June 2025, a drilling crew working near the Grand Canyon...
Unearthed a well of clean energy producing almost 8 times the output of the largest oil well in Saudi Arabia...
Capable of powering civilization for two million years.
Right here on American soil.
Everything changed that day.
Google signed a 15-year contract...
Bill Gates wrote a $100 million check.
And on July 4th, the government handed this energy source its biggest advantage ever.
One company owns the entire chain.
Yesterday's deadline is behind us.
Now every day you wait, the "early investor" window gets smaller.
I recommend placing your trade at tomorrow's market open.
Go here now for the Grand Canyon breakthrough ticker >>
"The Buck Stops Here,"
Dylan Jovine, CEO and Founder
Behind the Markets
More Reading from MarketBeat
Cologuard Is Working—So Why Isn’t Abbott Stock?
Submitted by Chris Markoch. Publication Date: 10/22/2026.
Key Points
- Abbott Laboratories shares fell about 4% after third-quarter results beat revenue expectations but failed to impress investors seeking stronger growth.
- The company announced plans to separate its Nutrition business, home to brands like Similac and Ensure, into an independent public company by the end of 2027.
- Abbott lowered its full-year comparable sales growth outlook to about 6% while narrowing adjusted EPS guidance to a range of $5.50 to $5.55.
- Special Report: Elon’s AI Masterkey — Get In Before December 8th
Abbott Laboratories (NYSE: ABT) delivered its third-quarter earnings report on Oct. 21. The stock dropped about 4% in early trading as investors, who were looking for something spectacular, got results that were merely solid.
Revenue of $13.01 billion edged out expectations of $12.99 billion. Sales rose 14.5% on a reported basis, boosted by the Exact Sciences acquisition, and 7% on a comparable basis, which accounts for the acquisition in both periods.
Adjusted earnings per share (EPS) of $1.42 were in line with expectations. Both revenue and EPS were higher year over year (YOY), however. In Q3 2025, revenue was $11.37 billion and adjusted EPS was $1.30. That works out to 9% earnings growth, and CEO Robert Ford noted that both sales and earnings accelerated compared with the first half of the year.
Where the Growth Is Coming From
This continues a story that began last quarter, when Abbott began to see revenue growth following its acquisition of Exact Sciences. That growth, which included the colon cancer screening tool Cologuard, continued in Q3. However, management was cautious about its guidance for future acceleration, which could be putting pressure on shares.
Diagnostics sales jumped 46.7% to $3.31 billion on a reported basis, but rose only 6.4% on a comparable basis. The Cancer Diagnostics segment, which houses the former Exact Sciences businesses, generated $968 million in sales, up 13.8% on a comparable basis. Cologuard led the way, with contributions from Exact’s precision oncology and international businesses.
Medical Devices remained Abbott’s largest segment, with sales of $5.83 billion, up 7.8% on a comparable basis. Electrophysiology grew in the mid-teens, or the high teens when excluding left atrial appendage (LAA) products. Management described this as the early stage of a growth acceleration phase for the business.
Why Investors Are Selling the News
One reason for the drop in Abbott's stock is that the company's earnings report came on Oct. 21, the morning after SpaceX (NASDAQ: SPCX) delivered a strong earnings report. That sent money flowing back into the technology sector and left blue-chip names like ABT vulnerable to selling.
Abbott also used its earnings release to announce plans to separate its Nutrition business into an independent, publicly traded company. That business is home to brands such as Similac, PediaSure, Pedialyte, Glucerna, and Ensure. The company says the separation will be structured as a tax-free distribution to shareholders and is expected to be completed by the end of 2027. Over the long term, the move could sharpen Abbott’s focus on medical devices and diagnostics. In the short term, it adds complexity for investors trying to value the company.
But Abbott's earnings report also gave investors more immediate reasons for concern. The company lowered its full-year comparable sales growth outlook to about 6%, down from its prior range of 6.5% to 7.5%, citing headwinds in diabetes care and electrophysiology. Even so, management expects fourth-quarter sales growth to accelerate to just above 8%.
Abbott also narrowed its full-year adjusted EPS guidance to $5.50 to $5.55, from $5.45 to $5.60, leaving the midpoint essentially unchanged. Even at the low end of that guidance, adjusted EPS would be up nearly 7% from $5.15 in 2025.
That’s still below the $5.55 to $5.80 range the company issued in January, before dilution from the Exact Sciences deal was factored in. Investors may also be concerned that Abbott's 2027 outlook will fall short of expectations, given management's plans to issue conservative guidance in January.
ABT Needs to Reclaim Its Moving Averages
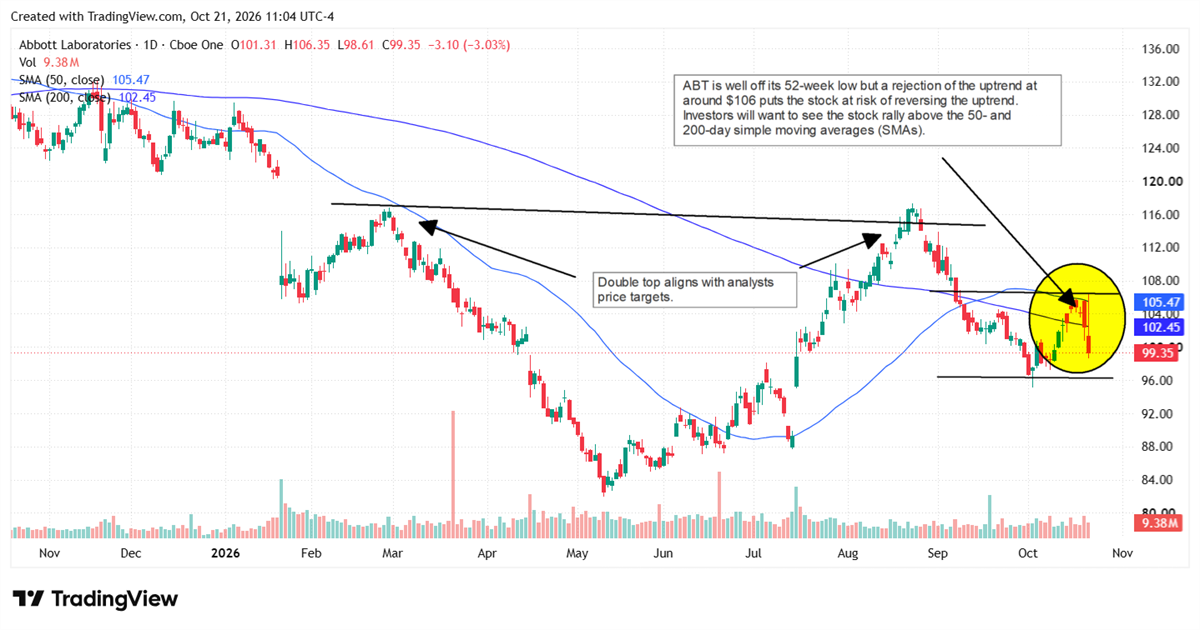
On the chart, ABT is range-bound between about $83 and $117. The top of that range is now a well-defined double top. The near-term concern is that the latest swing fell well short of that level. The 50-day moving average is flattening above a 200-day moving average that’s still sloping down, so the August golden cross may be close to unwinding.
Investors will want to watch the 50- and 200-day simple moving averages closely. If ABT can reclaim those levels on strong volume, a case may be made for a cup-and-handle formation. Until then, the near-term levels to watch are $95–$96 (the October low) and $106 (where the latest rally was rejected).
Analysts May Provide the Juice
As of this writing, the Abbott Labs analyst forecasts on MarketBeat show a consensus price target of $118.88. That implies a gain of about 20% and aligns with the double top the stock formed in March and August.
That potential 20% gain would be in addition to the stock's dividend, which yields 2.5%. ABT is also a dividend king with a 54-year streak of increasing its dividend payout. The dividend is well supported by the company's projected cash flow. Income investors don’t need to worry about the spinoff, either. Abbott expects the combined dividend paid by Abbott and the new Nutrition company to equal Abbott’s dividend at the time of the separation.
. |


